
 Контакт
 Как се пазарува?

Доставка
Наръчник за пазаруване
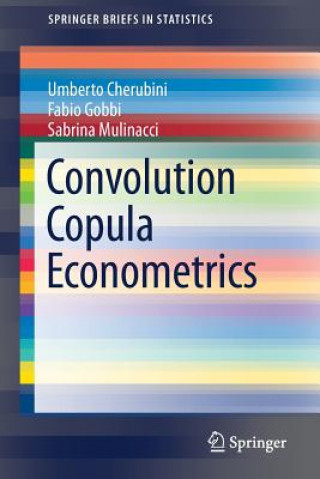
Convolution Copula Econometrics
 Английски език
 158 b
 Доставка до Коледа ▾
Външен склад
Изпращаме след 9-13 дни
До 30 дни за връщане на стоки
Клиентите са закупили също
 /
 С твърди корици
 119.15
€
233.03 лв
 /
С меки корици
107.47
€
210.19 лв










This book presents a novel approach to time series econometrics, which studies the behavior of nonlinear stochastic processes. This approach allows for an arbitrary dependence structure in the increments and provides a generalization with respect to the standard linear independent increments assumption of classical time series models. The book offers a solution to the problem of a general semiparametric approach, which is given by a concept called C-convolution (convolution of dependent variables), and the corresponding theory of convolution-based copulas. Intended for econometrics and statistics scholars with a special interest in time series analysis and copula functions (or other nonparametric approaches), the book is also useful for doctoral students with a basic knowledge of copula functions wanting to learn about the latest research developments in the field.


Информация за книгата
Английски език

Подарете тази книга днес
Лесно е
1 Добавете книгата в количката си и изберете Доставка като подарък 2 В замяна ще ви изпратим ваучер 3 Книгата ще пристигне на адреса на получателяМоже би ще Ви заинтересува

 /
С меки корици
74.29
€
145.30 лв
 /
С меки корици
20.94
€
40.95 лв






Здравейте! Аз съм Libroamiko, вашият книжен съветник.
Как мога да ви помогна?